Solana
| Market | Mark | Change | Best ask | Executable depth | Basis | Tier |
|---|---|---|---|---|---|---|
| $1,346.46 | +1.67% | $0.05 | $4,016,844 | n/a | Tier 2 | |
| $1,014.67 | +1.38% | $0.05 | $2,157,412 | n/a | Tier 2 | |
| $854.88 | −3.15% | $0.27 | $1,732,430 | n/a | Tier 2 | |
| $764.53 | −0.13% | $0.05 | $1,546,250 | n/a | Tier 1 | |
| $118.22 | +1.16% | $0.14 | $1,232,328 | n/a | Tier 2 | |
| $224.18 | −0.65% | $0.05 | $922,073 | n/a | Tier 1 |



| Upside at | Premium / share | Cost for 10 | Break-even | Max loss | Move needed | Fillable | |
|---|---|---|---|---|---|---|---|
$770.60per share right to buy through Sat, Sep 26 | $1.20 | $11.97 | $771.79 | −$11.98 | +1.0% | 251 SPYx | |
$790.48per share right to buy through Sat, Sep 26 | $0.05 | $0.50 | $790.53 | −$0.50 | +3.4% | 251 SPYx |
Contracts can expire worthless. Maximum loss is the premium plus fees. Exercising a call requires paying the strike.
 Pyth
 xStocks
 Solana
 Jupiter
 PreStocks
 Surfpool
 tokens.xyz
The problem, told plainly
Tokenized stocks trade 168 hours a week. The shares behind them trade 32.5, about 19% of the week. In the 75 hours between Friday's close and Monday's open, the token book is thin, the share has no price, and a leveraged position can be liquidated on a move the market will never confirm.
The engine sees a mark and defends it with your margin.
The contract sees a strike and an expiry. Nothing else.
The exchange closes. The perp keeps a mark from a book that is now the only price in the world for 75 hours.
10x long, 10 SPYx notional $7,645, margin $765Strike, expiry and premium are fixed. There is no mark to defend and no margin to top up.
Upside $771 on 10 SPYx, premium $11.97A sale into a thin token book prints a price the share never traded at. The perp's mark follows it.
mark −11% to $680.43The token price moved. The contract did not. The holder is asleep and owes nobody anything.
position unchangedMargin below maintenance, the engine closes the position at the wick. The market will never confirm the price.
$765 margin gone, position closedMax loss is still the premium. Whatever the book does, the worst case was printed on Friday.
max loss −$11.97The move the perp was liquidated on reverses at the open. The position that would have paid is gone.
opens at $810.40The buyer can exercise now or hold to Friday. Exercising means paying the strike and receiving the tokens.
intrinsic $398.03 on 10 SPYxThe whole margin, taken on a move the market never confirmed, on an asset whose market was closed.
Up, down or flat, the most the weekend could cost was known before the click. That is the whole product.
Every tokenized stock that can be escrowed safely is listed. Where our capital quotes is a published rule, not a promise, and a market moves up a tier by filling, not by asking.
The treasury quotes every expiry, both sides, at three sizes.
The treasury quotes the nearest expiry and pre-creates the next as it approaches.
Tradable the moment someone quotes it; the treasury holds no capital there.
The rest of the week the token is the only price in the world for Nvidia. A perp defends a mark through those hours with your margin. A contract with a fixed strike has nothing to defend.
168 hours a week for the token, 32.5 for the share (five sessions of 6.5 hours), 75 between Friday's close and Monday's open. NYSE holidays lower the 32.5 further.
$376.3B of perpetuals against $7.5B of spot on tokenized equities (CoinGecko, September 2026). The demand is for leverage.
What you can do here
Real numbers from the live quoter at the nearest expiry. Drag the expected price and watch the profit move while the maximum loss stays where it is.
Pay $11.97 for the right to buy 10 SPYx at $770.60 through Friday.
If it opens at $795, you're up $232.07. If it doesn't get there, you lost $11.97 and nothing else.
What we sell
Underneath, fully collateralized contracts on tokenized stocks and pre-IPO tokens, physically settled in the token. On the button, one benefit: priced and funded before you click.
Every screen does one job. The buyer understands the bet before the instrument: cost, break-even and the worst case are on the table before the wallet is. After the purchase, nobody is left wondering what happens next.
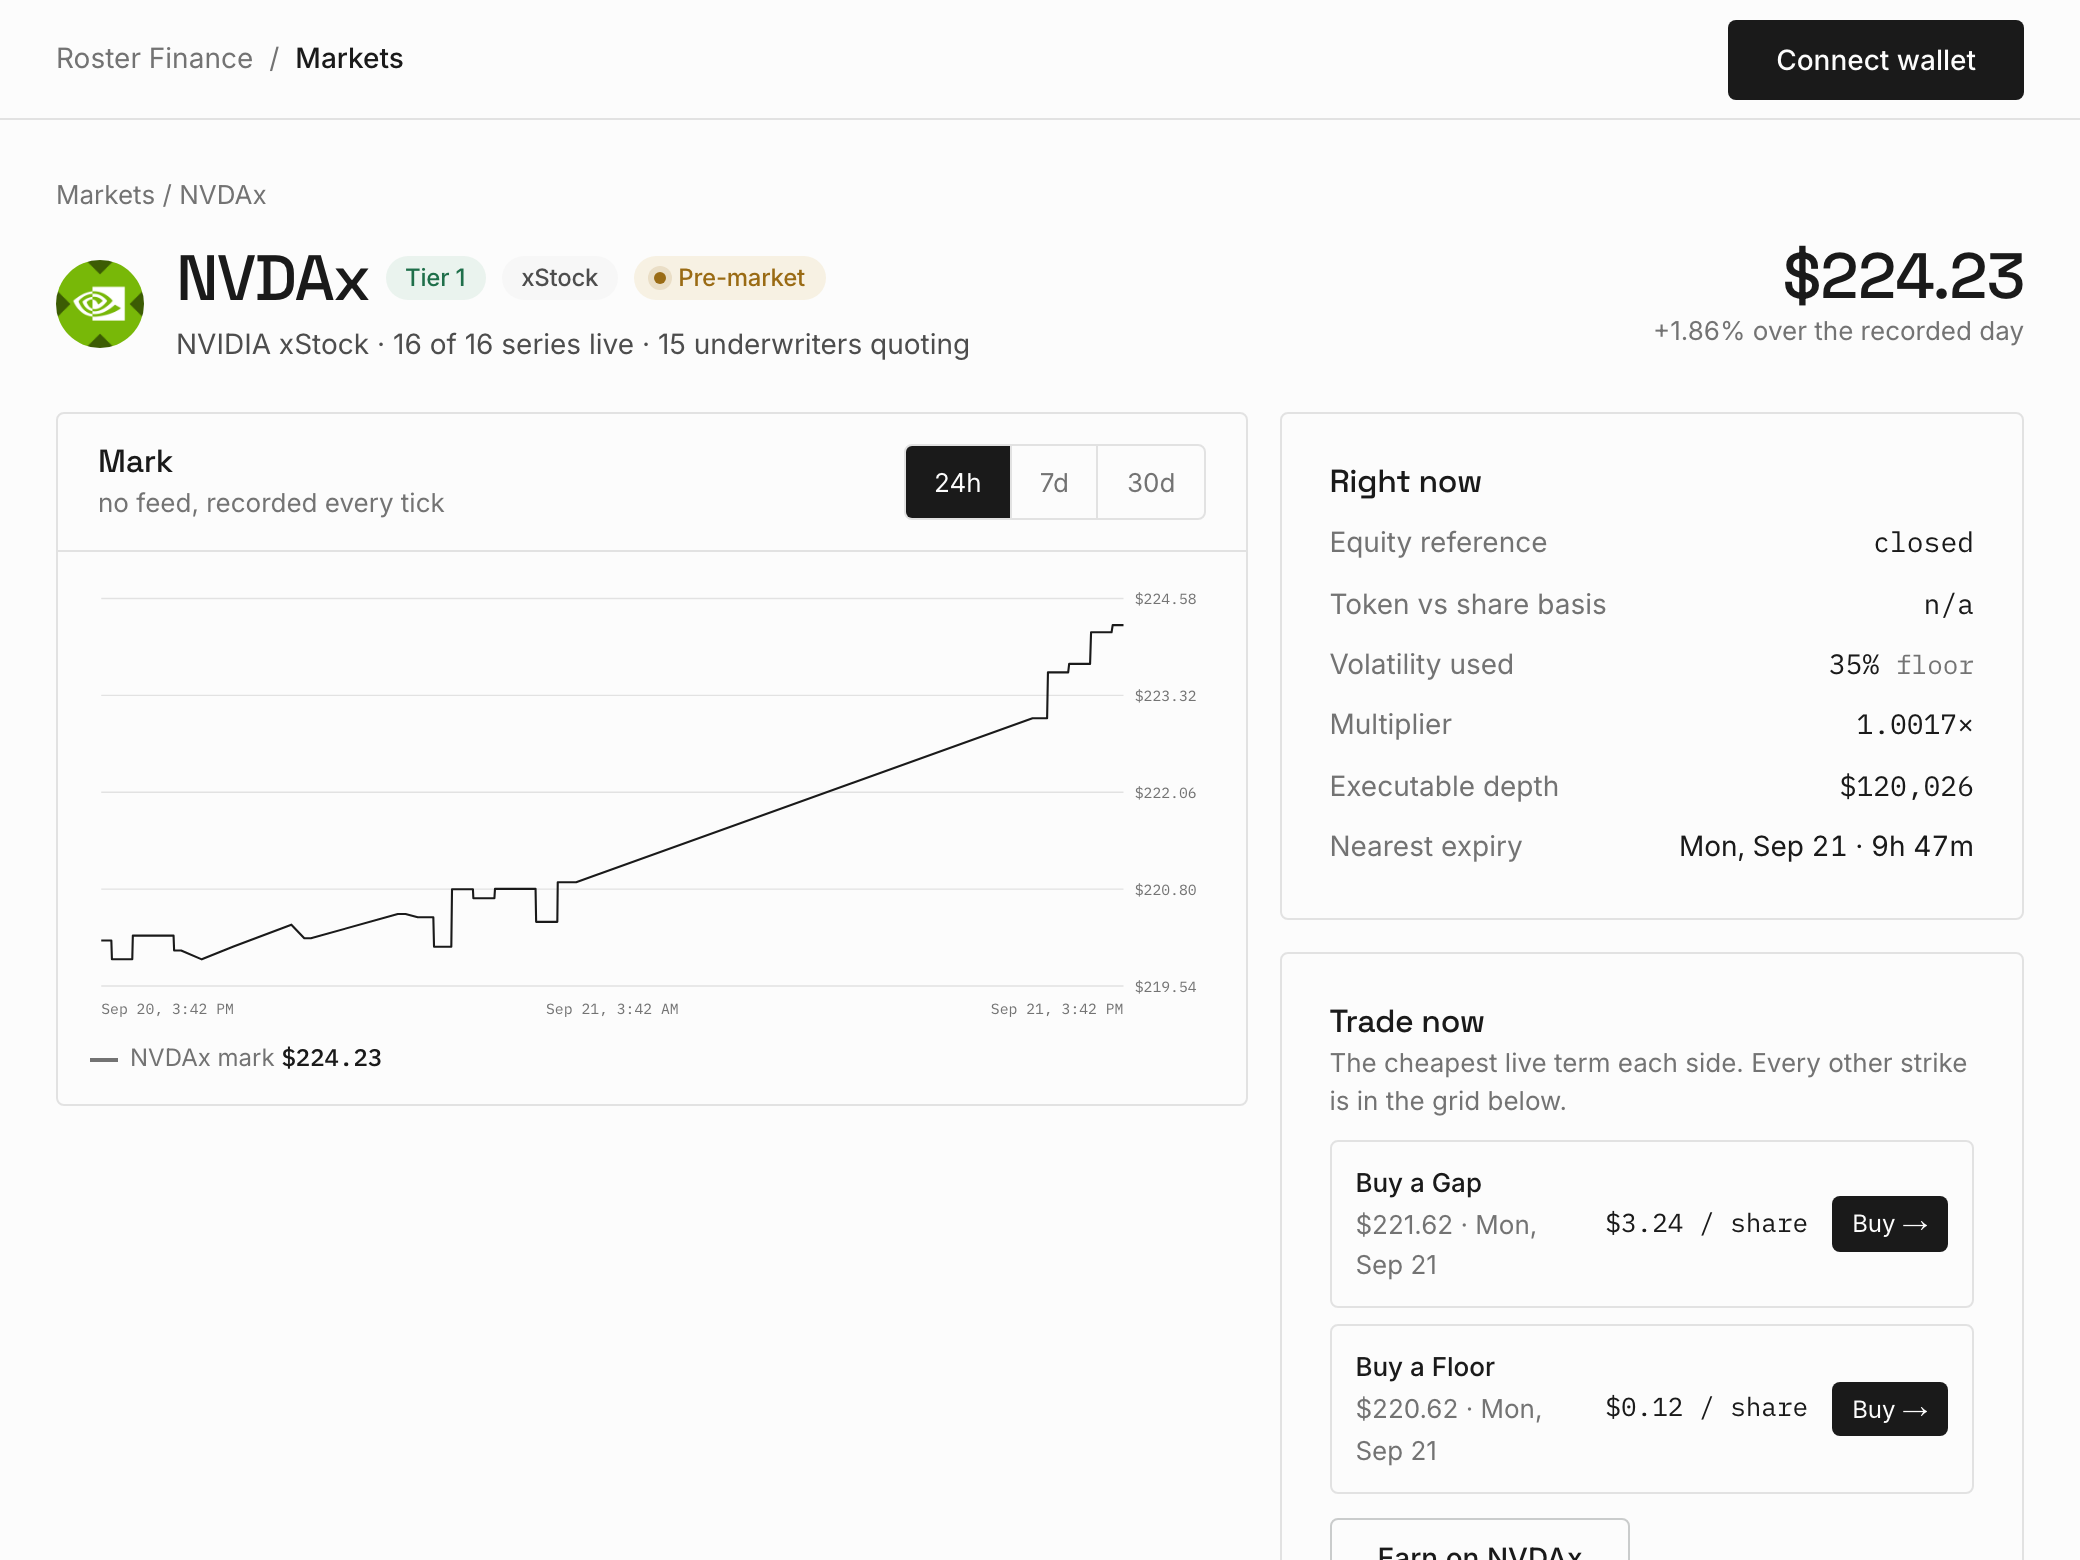
Perps take your position on the wick. Roster caps your loss at the premium and settles in the token itself, into your wallet. Today on Solana the only ways to lever a stock are a perp or a loan loop, and both liquidate; listed options cap the loss but close on Friday. Roster is the fourth column.
| Perps Hyperliquid, CEX stock perps, Wasabi | Loops Kamino, Loopscale | Listed options CBOE | Roster Finance fully collateralized, on Solana | |
|---|---|---|---|---|
| Max loss | Unbounded, liquidation | Collateral liquidation | Premium | Premium |
| Coverage | A few dozen synthetic names | The lending markets' collateral list | Every listed US name | 14 listed markets, 3 quoted by the treasury |
| Funding or interest | Yes | Yes | No | No |
| Open on Saturday | Yes, synthetic mark | Yes | No | Yes |
| Settles into your wallet | No | No | No | Yes, the token itself |
| Oracle-free settlement | No, the oracle mark closes you out | No, the oracle mark closes you out | Yes for stock options | Yes, exercise reads no price |
| Can liquidate you | Yes | Yes | No | No |
Open on Saturday across, worst case known up. Every incumbent sits in a corner that gives one up. The shaded quadrant is where a bounded loss and a weekend book meet. That is the fourth column, drawn.
Proof of executable protection
The live roster: quotes at three sizes, USDC and SPYx reserved with the accounts, capacity, and the exercise history. A venue that publishes whether its promises are funded is a venue that expects to be checked.
| Size | Per share | Cost | Makers in fill |
|---|---|---|---|
| 10 SPYx | $1.20 | $11.97 | 1 |
| 50 SPYx | $1.20 | $59.83 | 1 |
| 200 SPYx | $1.20 | $239.33 | 1 |
| Maker | USDC | SPYx | Account |
|---|---|---|---|
| Roster treasury | $572,500 | 1,257 | AuLv…7EqD |
| Date | Event | Size | Signature |
|---|---|---|---|
| Sep 25 | Exercise | 9.943179 SPYx | 4iye…W4vh |
The objections we expect, answered before they are raised. Never a claim to have invented a derivative.
Mechanically these are fully collateralized American options, and the docs say so. What we sell is one benefit: leverage or an exit with a known worst case, priced and funded before you click. No chain of strikes, no greeks, one underlying.
PreStocks tokens trade on chain before the company does, above or below the issuer's mark for months with no print to anchor them. A funded price on a date is the only way to know what you will get.
- ✓Priced off where the token trades, never the mark
- ✓Both figures on every ticket, the spread named
- ✓Exercisable any time until expiry
- ✓The mint's transfer fee stated in numbers
- ✓No ownership, voting or dividend rights
- ✓USDC locked before you buy
- ✓Sell at the strike any time through the date
- ✓Settles in the token itself, no oracle
- ✓Fee delivered on top so writers are paid to the unit
- ✓IPO and deal terms from the issuer on the ticket
- ✓Eight tokens from the issuer's API, live
- ✓Implied valuation both ways
- ✓Recent volatility measured, not assumed
- ✓Listed as escrow is proven, tier by tier
- ✓Paid risk, disclosed as such, never yield
Every figure on this page has a date and a source. Where a source's point concerned a different asset, the line says so.
September 2026
Perpetuals on tokenized equities did $376.3B against $7.5B of spot. The demand is for leverage; the instrument for it is the one that can't liquidate you.